

Practice
Gilda Bueno has over 20 years of experience as an office manager for a private family office in New York City.
Qualifications
Languages
- English
- Spanish
News
Ruchelman P.L.L.C. is pleased to announce that Neha Rastogi will be a Member of the Firm effective as of January 1, 2026.


Congratulations to Neha Rastogi on her admission to the New York State Bar and newly-minted status as an Associate at Ruchelman P.L.L.C.

Congratulations to Neha Rastogi, Law Clerk and Advocate (admitted in India), on passing the New York Bar Exam.
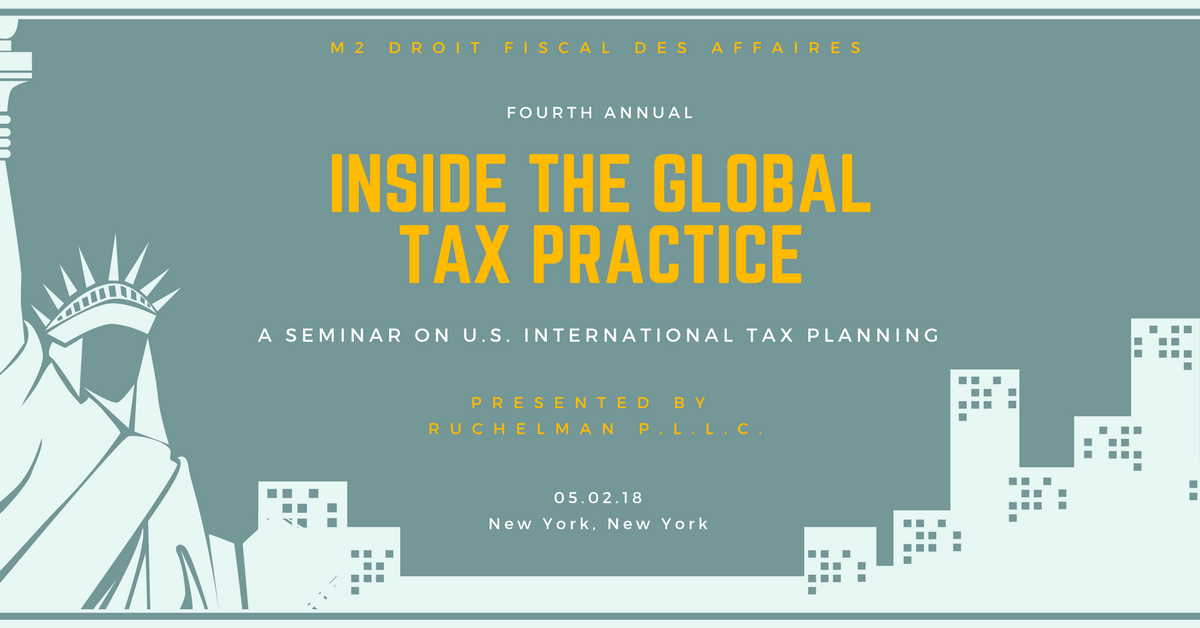
Ruchelman was delighted to host the students of the Université de Rennes I M2 Droit Fiscal des Affaires program for the 4th Annual Inside the Global Tax Practice.
Insights
Forming a Delaware corporation or limited liability company (“L.L.C.”) is remarkably easy. Remembering what to do with its internal records afterwards can be another matter. Corporate attorneys are frequently asked to form corporations and limited liability companies for use as blockers, holding companies, or acquisition vehicles in connection with a transaction. The entity itself may be only a small part of a much larger transaction, with most of the attention being paid to the purchase agreement, financing documents, or other agreements that is entered into by the newly formed entity. Once the transaction is completed, however, the internal corporate records of the newly formed entity can easily become an afterthought. The issue often resurfaces months or years later when a lender, purchaser, investor, or foreign counsel asks to see them. In his article, Simon Prisk looks at the various ancillary documents that are executed and then frequently ignored by clients that do not have an internal legal department. Examples include (i) certificates of formation, (ii) bylaws, (iii) subscription agreements, (iv) amendments to reflect changes to formal ownership records, and (v) a physical or digital minute book.
Over the past several years, the I.R.S. has targeted tax-free partnership transactions designed to shift tax basis to property in a way that will yield tax savings for the partner, the partnership, or both. The goal of these transactions is to use the interplay of rules governing inside basis and outside basis to shift tax basis from assets where it is less beneficial for income tax purposes to assets where a higher basis provides greater benefits, i.e., because the asset offers greater cost-recovery deductions or smaller taxable gains when sold. Regulations were adopted in final form during the last days of the Biden Administration, but were withdrawn in Notice 2025-23, with effect as of the date of their issuance. In his article, Wooyoung Lee (i) observes that, while the regulations were withdrawn, the I.R.S. has not withdrawn Rev. Rul. 2024-14, which accompanied the proposed regulations when issued in 2024 and explains the three types of basis-shifting transactions that, in the view of the I.R.S., fail the economic substance doctrine that is codified in Code §7701(o).
Foreign owners of single member U.S. limited liability companies (“L.L.C.’s”) are often told that an L.L.C. with one member is a disregarded entity for U.S. tax purposes. They assume that it means exactly that: disregarded. The assumption is understandable. It was true in almost every relevant respect for many years. It is still true for U.S. income tax purposes. A single-member L.L.C. generally files no income tax return of its own. Its income, deductions, and assets belong to its owner. But the assumption is wrong in one important respect. Since 2017, a foreign-owned single-member L.L.C. has been treated as a domestic corporation for purposes of the reporting and record-maintenance obligations under Code §6038A, involving transactions between the L.L.C. and its foreign related parties. The reporting mechanism is Form 5472 (Information Return of a 25% Foreign-Owned U.S. Corporation or a Foreign Corporation Engaged in a U.S. Trade or Business.) The I.R.S. instructions confirm that a reporting corporation includes a ≥25% foreign-owned U.S. corporation, including a foreign-owned U.S. disregarded entity. On April 24, 2026, the I.R.S. released Chief Counsel Advice 202617012 (“C.C.A.”). The C.C.A. addresses when the reasonable cause exception to the Code §6038A penalty applies and, in particular, what it means for the I.R.S. to apply that exception “liberally” for certain small corporations. In her article, Galia Antebi explains (i) Code §6038, (ii) the reasonable cause standard in Treas. Reg. §1.6038A-4(b), and (c) how that standard was applied in the C.C.A. While the C.C.A. may not be used or cited as precedent, it serves to illustrate how the I.R.S. evaluates reasonable cause at the time of the C.C.A.’s issuance.
For many non-U.S. individuals, obtaining a U.S. Individual Taxpayer Identification Number ("I.T.I.N.") represents their first substantive interaction with the U.S. tax system. At first glance, the process may appear relatively straightforward: complete Form W-7, provide the required supporting documentation, submit the application to the I.R.S., and await issuance of the I.T.I.N. In practice, however, the process is considerably more nuanced. All of these steps must be coordinated through an I.R.S. Certifying Acceptance Agent ("C.A.A."), assuming the individual does not wish include his or her passport in the packet of documents sent to the I.R.S. In his article, David te Boekhorst, the Founder and the Director of Angularis Global Services Inc., offers practical observations drawn from true life experience working in coordination with legal and tax advisors to assist international clients in navigating the administrative and compliance-related dimensions of the I.T.I.N. application process. He addresses (i) the purpose of the I.T.I.N. program, (ii) the role and responsibilities of the C.A.A., (iii) common misconceptions surrounding I.T.I.N.’s, and (iv) practical lessons learned from guiding foreign individuals through the application process.
Legal systems regarding taxation differ significantly between jurisdictions, and legal vehicles used to attain a specific goal often must be revised when a border is crossed. A clear illustration of this is the discretionary trust, which is a common estate planning tool in the U.S., but is often associated with tax avoidance schemes in the Netherlands. For that reason, assets, liabilities, and income of a discretionary trust are attributed to the contributor under the Afgezonderd Particulier Vermogen (“A.P.V.”) regime. An A.P.V. is defined as a segregated estate that is intended to serve a private interest that is more than incidental. In their article, Stan Stevens, a Partner at HVK Stevens Tax and Legal in Amsterdam, and Sandra Singh, a Director at the same firm, explain the rules and how they are applied in troublesome fact patterns, including unexpectedly harsh treatment if (i) a contributor of a trust moves to the Netherlands, (ii) a nonresident contributor arranges for the trust to have Dutch source income, (iii) a nonresident contributor owns Dutch situs assets at the time of death, or (iv) a Dutch expat individual dies within ten years from the date of expatriation.
No rule is more easily ignored than one no one seems to have heard of, and few provisions of French tax law make the point as neatly as the annual 3% tax on the fair market value of French real estate held by legal entities (taxe annuelle sur la valeur vénale des immeubles). Indeed, while having a very broad scope – the 3% tax is never far away where a French real estate property is not owned directly by an individual – it seems to be often overlooked by international investors, exposing them to significant tax risks. The 3% tax was initially conceived as a tracking device to seek out individuals attempting to avoid wealth tax or registration duty. Assessment of the tax is not time-barred until the end of the sixth year following the year involved, leading in the most egregious case to a 21% tax based on the real estate value. In their article, Xenia Lordkipanidze, a Partner in the Tax Department of OVERSHIELD Avocats, Paris, and Clement Pere, a Senior Associate in the Tax Department at the same firm, take a deep dive into the rules, explaining (i) how the tax is computed when a chain of corporations stands between the individual and the property, (ii) the persons who a deemed to be authorized to receive notices from the French Tax Authority, (iii) the 30-day grace period to file late that is offered to first time offenders, (iv) seven applicable exemptions to the 3% tax, (v) adverse case law for persons and entities that challenge the tax, and (vi) several items of practical guidance for affected individuals.
With a coalition government in office for 19 months, Belgium is making progress on the implementation of the ambitious tax reform that was announced when the new government was about to be sworn in. Although progress is real, it is taking shape piece by piece instead of one massive overhaul. In their article, Werner Heyvaert, Of Counsel at Advisius Tax & Legal in Brussels, and Yannick Vandenplas, an Associate at the same firm, explain the myriad of changes adopted earlier this year, including (i) the introduction of a broad capital gains tax on financial assets for Belgian individual taxpayers, followed up in administrative guidance that was issued in July, (ii) stricter rules for the dividends received deduction for Belgian corporations and for the dividend withholding tax exemption allowed to nonresident corporations, (iii) changes to the company exit tax regime, allowing for taxation of the “Liquidation Bonus” realized by individual shareholders, (iv) the adoption of a special tax regime for “carried interests,” (v) an overhaul of the tax regime for newly arrived expats, (vi) a revision to the Investment Deduction regime, a tax incentive allowing Belgian businesses to deduct a notional portion of the purchase price or investment cost of qualifying fixed assets made during the year, and (vii) the adoption of mandatory digital invoicing.
This month, Nina Krauthamer and Wooyoung Lee look briefly at two recent developments in tax. The first addresses pied-à-terre homes in New York City. Following tax policies adopted by certain cities in Canada, a yearly property tax surcharge will be imposed on New York City homes worth $5 million or more when (i) the home is not used as a primary residence for the owner or for a family member or (ii) is not rented out on full-time basis to an individual who uses the unit as a primary residence. The second development is reported by an anonymous source in contact with an unnamed immigration lawyer. According to the source, the I.R.S. is considering a change to Form 1040 (U.S. Individual Income Tax Return) to add two check boxes to the form. One will be used to indicate (a) whether the resident filer is or is not a U.S. citizen. The second will be used to identify w
In May, the I.R.S. announced a settlement offer for partnerships involved in disputes concerning “syndicated conservation easements.” The dispute involves the value of charitable deductions claimed in regard to the grant of an easement that prevents the owner from developing land. An easement is a legal right that allows one party to use a specific portion of someone else’s property for a specific, limited purpose without actually owning the land. The grant purportedly becomes a tax shelter when (i) multiple unrelated investors (ii) pool their money in a partnership or syndicate (iii) that is formed to acquire various parcels of undeveloped land (iv) for the principal purpose of contributing development rights to a land trust, (v) that allows the investors to claim charitable contribution deductions at purportedly inflated values far in excess of the investment in the land. In their article, Stanley C. Ruchelman and Wooyoung Lee explain the history of this typically U.S. centric tax shelter to readers outside the U.S.

“Q.S.B.S.” is a tax related acronym in the U.S. for Qualified Small Business Stock. When a start-up corporation meets certain conditions enumerated in Code §1202, noncorporate investors are offered the opportunity to derive tax-free capital gains by holding the investment for a period of time prior to a liquidity event. The greater of $10 million of gain or 10 times the taxpayer’s basis in the Q.S.B.S. – referred to as “basis loading – may be exempt from tax on exit. The tax benefit can be enhanced by creating multiple irrevocable nongrantor trusts, each formed for the benefit of a specific family member. Each trust is entitled to its own capital gain exemption, so long as the multiple trust rule of Code §643(f) is not triggered. Under that rule, multiple trusts having (i) the same grantor, (ii) substantially the same primary beneficiaries, and (iii) an income tax avoidance purpose are treated as a single trust.. Among savvy investors, the tax plan is known as “stacking.” In her article, Galia Antebi reports that Treasury Assistant Secretary for Tax Policy Kenneth Kies recently signaled that Treasury does not like stacking. The bad news is that forthcoming Q.S.B.S. guidance is expected to limit taxpayers’ ability to multiply the benefit. The good news is that basis loading is not a target – at least for now.
When individuals consider moving their tax residence to Italy, the first conversation almost always begins with a specific question. How will I be taxed in Italy? It is a question that comes most naturally to clients who have read about Italy’s special regimes. But is it the only question that should be considered? In her article, Giada Mazzola, Senior Counsel at Caldara & Associati in Milan, cautions that an adviser who treats the first conversation as a tax-rate conversation will produce an answer that may be technically correct, but may be problematic for practical reasons related to the way the client chooses to live. A more useful approach is one that asks the five questions that all begin with the letter “W” – Who? What? When? Where? and Why? An adviser will be able to fashion a tax plan and a life plan that meets the needs of the client over the long haul only when those five questions are asked by the adviser and answered by the client (i) fully, (ii) completely, and (iii) honestly.
In the past year, the British Virgin Islands (“B.V.I.”) beneficial ownership information (“B.O.I.”) reporting regime moved from consultation and transition to implementation and enforcement in ways that may affect more than companies and their beneficial owners. Areas of the law that are potentially affected, include (i) beneficial and legal ownership and title, (ii) proprietary rights, (iii) shareholder disputes, (iv) creditor rights and secured lending, (v) fiduciary obligations, (vi) registered agent duties, (vii) privacy, (viii) cross-border confidentiality, and (ix) potential public law challenges to administrative decision-making.that may affect more than companies and their beneficial owners. In his article, Joshua Mangeot, a leading advisor on the implementation of the B.V.I. economic substance and beneficial ownership reporting requirements, points out that these are areas of the law that areprovides an update on the B.V.I. position, focusing on points most likely to matter to international tax advisors, family offices, corporate and fiduciary service providers, trustees, private banks, fund managers, litigators, and end-clients using B.V.I. companies or limited partnerships in cross-border structures. It raises potential issues regarding (i) beneficial and legal ownership and title, (ii) proprietary rights, (iii) shareholder disputes, (iv) creditor rights and secured lending, (v) fiduciary obligations, (vi) registered agent duties, (vii) privacy, (viii) cross-border confidentiality, and (ix) potential public law challenges to administrative decision-making. Clearly, the adoption of the B.O.I. reporting regime can be viewed to be the equivalent of the proverbial camel’s nose under the tent.
As more families live, invest, and hold assets across multiple countries, estate planning increasingly requires coordination between legal systems that are not designed to work together. A foreign Will, alone, may not effectively administer U.S. assets, while a U.S. Will drafted in isolation can unintentionally disrupt an existing foreign estate plan. An important objective in cross-border estate planning is the creation of complementary structures that minimize probate friction, provide efficient tax planning for beneficiaries, and preserve the client’s intended dispositive scheme across jurisdictions. In her article, Allison Dolzani (i) explores several key cross-border testamentary planning considerations for global families with U.S. beneficiaries and U.S. assets and (ii) suggests planning, practical, and logistical guidance for U.S. estate administration of a foreign estate.
The Supreme Court of India issued a landmark ruling in the case of three Mauritius entities owned by the Tiger Global Group in the U.S. The three entities were private companies incorporated in Mauritius. They were formed to undertake investment activities aimed at long-term capital appreciation and investment income. They were regulated by the Mauritius Financial Services Commission (“F.S.C.”) and held Category I Global Business Licenses under the Financial Services Act, 2007. Each held a valid Tax Resident Certificate issued by the Mauritius Revenue Authority, which certified their status as tax residents of Mauritius for income tax purposes. The Indian Supreme Court was unimpressed. The arrangement had the correct form, but in the facts presented, the form lacked economic substance. Abbas Jaorawala, a Senior Director and Head-Direct Tax of Khaitan Legal Associates, Mumbai, explains all.
The taxation of dividends paid by Portuguese resident companies to nonresident C.I.V.’s has become one of the most litigated and structurally significant issues in Portuguese tax law. What began as a technical discussion concerning the scope of a domestic tax exemption has evolved into a consolidated body of caselaw confirming a structural incompatibility between Portuguese tax legislation and European Union law, in particular the principle of free movement of capital. In his article, António Gaspar Schwalbach of Spear Legal, Lisbon, revisits the Portuguese tax regime applicable to dividends distributed to C.I.V.’s, and addresses the practical consequences for nonresident funds, asset managers, and custodians, including the recovery of withholding tax and indemnity interest.
The French Finance Act for 2026 introduced several measures affecting private wealth structuring and investment strategies. Some provisions were expected and were discussed in previous legislative debates. Others target specific structuring techniques traditionally used for wealth preservation or intergenerational planning. Philippe Stebler, of Stebler Moati Avocats, Paris, explains the tax provisions that were adopted, including (i) the extension of minimum income taxation of 20% for individuals, (ii) adjustments to the tax deferral regime applicable to share-for-share exchanges occurring before cash-outs through holding companies, (iii) the imposition of a new 20% tax is imposed on certain luxury assets held through holding companies, (iv) the exclusion of luxury assets held by companies from the “Dutreil” regime, a major tax relief mechanism for business transfers by gift or inheritance, and (v) an extension of the temporary surtax for large corporations.
Nirmala Sitharaman, the Indian Finance Minister, presented Budget 2026-27 on February 1, 2026. It promises significant tax benefits for nonresident investors operating in specific sectors of the economy. Jairaj Purandare, the Chairman of JMP Advisors Pvt. Ltd., Mumbai, Bhakti Shah, a Director of JMP Advisors Pvt. Ltd. in Mumbai, and Siddhita Desai, a Senior Associate at JMP Advisors Pvt. Ltd., Mumbai, take a deep dive into the budget. Highlights include (i) expansion of the preferential time periods for I.F.S.C. and O.B.U. tax benefits, (ii) an exemption for income of a foreign company that arises in India from procuring services from a specified data center in India, (iii) an exemption for income of foreign companies arising from the provision of capital goods, equipment, or tooling to a contract manufacturer in India, (iv) an exemption for overseas income of a nonresident individual for five consecutive tax years where the nonresident visits India for the first time to render services under an approved program, (v) the adoption of a unified 15.5% safe harbor in the Indian transfer pricing rules for providing information technology services with a cap of U.S.$2.2 billion, and (vi) expansion of the benefit of an A.P.A. to cover affiliates of the taxpayer that applied for the A.P.A.
The economic substance doctrine has a long-standing history in U.S. tax law, stretching back over 90 years. Case law also developed other related doctrines, such as the business purpose doctrine and step-transaction doctrine, all of which attempted to answer the same question – was the business transaction real or was it a charade intended solely to reduce tax. Code §7701(o), entitled “Clarification of economic substance doctrine,” was enacted in 2010 to codify the preexisting regime. The legislative history provided an angel list of transactions that were not viewed abusive. For those transactions and others that did not contain hallmarks of tax avoidance, it was accepted that the economic substance doctrine was not relevant. Indeed, the statute provides that, with limited exception, if the economic substance doctrine was not relevant to a fact pattern prior to the enactment of Code §7701(o), the economic substance doctrine would not be relevant after the enactment of that provision. Then, in 2023, the I.R.S. put on its sheriff’s hat and turned the angel list into a hit list, taking the position that Code §7701(o) was a game changer. In their article, Stanley C. Ruchelman and Wooyoung Lee examine two recent cases, Liberty Global and Patel, in which the I.R.S. position was that case law was no longer relevant if planning became too aggressive. The I.R.S. won both cases, but the jury is out as to the validity of its position.
Carried interest tax regimes are under review across several countries in which major fund hubs are based. Policy trends diverge, with some jurisdictions tightening tax privileges in response to fairness and anti-avoidance debates, while others recalibrate to attract or retain fund talent and decision making substance within an investment fund context. Seeking to foster and strengthen its position as a major investment fund hub, the Luxembourg government proposed legislation to reform the existing carried interest regime. In his article, Adnand Sulejmani, a senior associate in the Luxembourg tax practice of Ashurst, explains that the existing law fostered inconsistent interpretations among practitioners regarding the taxation of carried interests and contained a sunset provision for the benefit. In comparison, the proposed legislation emphasizes tax certainty for participating investment management professionals and a permanent favorable tax regime. The proposed legislation is expected to be enacted before the end of January 2026, with an effective date as of January 1, 2026.
Colombia is a beautiful country, known for its unique biodiversity, natural landscapes, and cultural richness. It is the fourth largest economy in Latin America, and frequently serves as a regional operations platform for South America, Central America, and the Caribbean. However, tax rules in the country can be problematic. Foreign entrepreneurs providing consulting, technical, management, or administration services to local residents or businesses are subject to withholding tax at rates between 20% and 33%. Foreign providers of streaming services, online ads, data management, and digital goods may be subject to a gross tax based on sales that is triggered by reason of having a significant economic presence in the country. Other foreign companies may trip into worldwide tax exposure if Colombia is viewed to be the effective place of management of the company. The threshold for this risk is low as the risk potentially exists from short-term presence in Colombia by executives or employees. Finally, the standard under which an individual is viewed to be tax resident is not straightforward. In his article, Eric Thompson, a partner of attorneys Cañón Thompson, Bogota, identifies the various areas of risk and cautions that companies trading with Colombia or individuals who move to Colombia require careful advance planning.
Vietnam has emerged as one of Southeast Asia’s most dynamic investment destinations, supported by strong economic growth, a large and increasingly skilled workforce, and deep integration into the global trading system through numerous free trade agreements. Ho Chi Minh City plays a central role in attracting foreign direct investment, particularly in manufacturing, services, technology, logistics, and consumer-related industries. In their article, Nguyen Thi Quynh, the managing partner at Eruditus Legal, Ho Chi Minh City, and Nguyen Thi Hang Nga, a tax partner at Eruditus Legal, Ho Chi Minh City, provide a practical overview of the key legal and regulatory considerations that foreign investors should take into account before investing in the country. Topics covered address investment structures, licensing requirements, corporate income tax, value-added tax, special consumption tax, and import and export duties.
India has been at the forefront of implementing B.E.P.S. measures. It submitted a ratified M.L.I. with the O.E.C.D. in 2019, with effect from April 1, 2020. However, the Indian Parliament never enacted legislation amending all covered income tax treaties. Relying on a relatively recent Supreme Court of India case involving the relationship between income tax treaties and domestic law (Nestle SA), the Income-Tax Appellate Tribunal (“I.T.A.T.”) for Mumbai held that until Parliament enacts legislation adopting an income tax treaty, the treaty is not the law of the land (Sky High Appeal XLIII Leasing Company Ltd). Abbas Jaorawala, a Senior Director and Head-Direct Tax of Khaitan Legal Associates, Mumbai, discusses the interesting conundrum faced by the Indian tax authorities. On one hand, they can continue litigating the matter, but victory is uncertain and a favorable decision by the Supreme Court is not assured by reason of the Nestle SA case. On the other hand, legislation can be enacted quickly, but it is not clear it can be effective on a retroactive basis.
In Canada v. Cameco Corporation, the Canada Revenue Agency (“C.R.A.”) challenged Cameco's transfer pricing arrangements with its Swiss subsidiary during the early years of the twenty-first century. In 2018, the Tax Court of Canada ruled in favor of Cameco, finding that the transactions were not shams and were conducted on arm's length terms. In 2020, the Federal Court of Appeal unanimously upheld the decision, rejecting the C.R.A.'s arguments that profits were inappropriately shifted. The recent Canadian federal budget introduced new Canadian transfer pricing legislation containing the most consequential change since 1997. In his article, Michael Peggs explains that the amendment has something for everyone: a response to the decision in Cameco, alignment with O.E.C.D. guidance, and harmonization with treaty partners.
Remote work is one of COVID-19’s enduring legacies. What began as something necessary for health and safety reasons has become a fairly conventional practice. Not surprisingly, issues have arisen related to remote work locations as permanent establishments when an individual resides in Contracting State 1 and works for an employer based in Contracting State 2. In November, the O.E.C.D. issued additional guidance to the permanent establishment article of the Model Tax Convention on Income and on Capital, without changing any of the text of the article. The updated commentary emphasizes that general principles for determining the existence of a P.E. – such as the permanence of the premises and whether the premises are used to carry out core business functions rather than ancillary functions – apply in evaluating whether the employer based in Contracting State 2 maintains a P.E. in Contracting State 1 by reason of a home office of an employee located in Contracting State 1. In their article, Stanley C. Ruchelman and Wooyoung Lee explain that the new guidance focuses principally on two factors: time spent working out of a remote worker’s home and commercial reasons for being in another country. Five examples of typical fact patterns are provided, of which four provide favorable outcomes. Companies with remote workers are encouraged to use the examples in drafting – and enforcing -- a remote worker policy that parrots the examples that reach favorable outcomes. Failure to do so will prolong the current system that yields uncertainty.
When a married couple resides in a civil law jurisdiction, ownership of marital property typically is governed by community property principles – rules that automatically characterize most assets acquired during marriage as jointly owned, regardless of the way ownership is titled. While these regimes provide clarity in a wholly domestic set of facts, they create significant uncertainty when a married couple has cross-border ties, particularly involving the U.S. The challenges become especially pronounced where one spouse is a U.S. citizen subject to U.S. Federal income, estate, and gift taxation on worldwide assets, while the other spouse is a nonresident, noncitizen (“N.R.N.C.”) individual for purposes of U.S. Federal income, estate, and gift taxes whose tax exposures typically are limited to U.S.-source income and U.S. situs property. In her article, Neha Rastogi addresses potentially problematic fact patterns for the married couple, including (i) ownership of life insurance, (ii) F.B.A.R. reporting, (iii) entity characterization of the ownership interests in a domestic L.L.C., and (iv) basis step-up for a surviving spouse when the other spouse’s lifetime comes to an end.
1. For over 100 years, individuals who were domiciled outside of the U.K. benefitted from the non-dom tax regime. Its features are well known. Individuals who were resident but not domiciled in the U.K. could defer the imposition of U.K. tax on income and gains derived from sources outside U.K. until such time as proceeds were remitted to the U.K. It also meant that only U.K. situs assets of an individual domiciled outside the U.K would be subject to U.K. inheritance tax (“I.H.T.”). Also commonly known is that the non-dom tax regime was abolished earlier this year, being replaced with a new system based on residency. The new system came into effect on April 6, 2025, coinciding with the start of the new fiscal year. In their article, Alexa Collis, a partner of Harbottle & Lewis L.L.P., London, and Claire Walsh, an associate at Harbottle & Lewis L.L.P, London, explain the key features of the new regime. L.T.R.’s, I.H.T., Tails to I.H.T., F.I.G., C.G.T., Tails to C.G.T. and T.R.F. are explained in the context of two case studies. One case study relates to a new arrival and the other relates to a departing person. In this manner, tax buzzwords are placed into real life context. Very helpful.
Several Indian transfer pricing cases regarding the treatment of marketing expenses are teed up for consideration by the Supreme Court of India. The cases challenge the assertion made by the Indian tax authorities (“I.T.A.”) that advertising, marketing, and promotion (“A.M.P.”) expenditures by Indian affiliates of foreign headquartered multinational groups typically reflect an embedded service that is provided for the benefit of the foreign headquarters company. Having made database searches focusing on the relationship of A.M.P. expenditures to sales of certain business classes, the I.T.A. asserts that local affiliates of foreign companies tend to spend significantly more on A.M.P. than comparable independently-owned Indian companies when A.M.P. is measured as a percentage of sales. The I.T.A. characterizes the excess expenditure as a brand-building service that benefits the foreign-based headquarters company. A fee should be charged for the performance of that service. The fee would be equal to the deemed excess amount plus an arm’s length mark-up. Sanjay Sanghvi, a senior partner in the Direct Tax Practice of the Mumbai office of Khaitan & Co., and Ujjval Gangwal, a principal associate in the Direct Tax Practice of the Mumbai office of Khaitan & Co., take a deep dive into the cases before the Supreme Court. They caution that a decision in favor or the I.T.A. likely will expose multinational groups based in the U.S. and other O.E.C.D. countries to international double taxation.

Greece’s diverse real estate market has become an increasingly attractive destination for foreign investment. The Mediterranean climate, rich cultural history, and growing economy make the country particularly appealing to investors looking for residential and commercial properties. Greece’s investment landscape is further enhanced by favorable tax incentives, such as the Non-Dom tax regime, the tax regime for pensioners, the tax regime for employees and freelancers, the family office regime, and the Golden Visa program. In their article, Natalia Skoulidou, a Partner of Iason Skouzos Tax Law, Athens, and Aikaterini D. Besini, a Senior Associate at Iason Skouzos Tax Law, Athens, provide a comprehensive overview of the tax landscape for foreign investors investing in Greek commercial real estate. Their article outlines the key tax considerations at each stage of the investment process to help investors navigate the complexities of Greece’s tax system in order to make well-informed strategic decisions. The outcome can be quite favorable to investors from abroad.

G.A.A.R. or S.A.A.R.? Effect of the Nordcurrent Decision in Belgium, the Netherlands, and Luxembourg
Earlier this year, the C.J.E.U. issued its anticipated judgment in the Nordcurrent case (C-228/24). The judgment concerns the extension of the anti-abuse rule in the E.U. Parent-Subsidiary Directive (“‘P.S.D.”) to national participation exemption mechanisms. The ruling has significant implications and resonance in Belgium and the Netherlands, less so in Luxembourg, In their article (1) Werner Heyvaert, a Partner, and Yannick Vandenplas, an Associate, in the Brussels office of AKD Benelux Lawyers, (2), Jan-Willem Beijk and Anton Akimov, Partners in the Netherlands practice of AKD Benelux Lawyers, and (3) Maria-Clara Vassil, a Senior Associate, and Sanja Vasic, an Associate in the Luxembourg office of AKD Benelux Lawyers provide a clear summary and analysis of the case, explore its practical implications in their respective countries, and offer a perspective on its broader impact.

An immovable asset is a plot of land or a structure built on the land. Neither can be moved without being damaged or without damaging the land to which it is attached. Certain rights are also immovable due to their intrinsic link to immovable assets. An example would be real estate property rights, such as those embedded in a usufruct arrangement. In comparison, a movable asset can be transported from one place to another or is intangible by its nature. The French Civil Code expressly includes shares of companies in the concept of movable assets, even where such companies own real estate. The historical distinction between immovable and movable property is why French tax law created an autonomous concept of a “predominantly real estate company.” The definition of a predominantly real estate company varies depending on the tax being imposed. In their article, Xenia Lordkipanidze, a Partner in Overshield Avocats, Paris, and Clement Pere, an Associate in the Tax Department of Overshield Avocats, Paris, explain the inconsistency of French law and cases. The Cour de Cassation, the French Supreme Court for non-administrative matters, has jurisdiction over disputes relating to gift and inheritance duties and wealth tax has reached one conclusion – shares comprise movable property. The Conseil d’Etat, the French Supreme Court for administrative matters has jurisdiction over disputes relating to personal and corporate income tax, including capital gains tax, has reached a contradictory conclusion – shares of a predominantly real estate company comprise immovable property. The question posed by the authors is which Supreme Court reached the correct answer. Not surprisingly, the answer given is that it depends on relevant factors.
Ruchelman P.L.L.C. | 150 East 58th Street, 22nd Floor | New York, N.Y. 10155 | T. 212.755.3333 | F. 212.755.5898
Disclaimer | Privacy Policy | Attorney Advertising
© 2026 Ruchelman P.L.L.C. All rights reserved.
Disclaimer | Privacy Policy | Attorney Advertising
© 2026 Ruchelman P.L.L.C. All rights reserved.